Operational due diligence: the questions financial diligence misses
The quality of earnings report tells you what the business earned. Operational diligence tells you whether it can keep earning it, and what it will cost to grow.
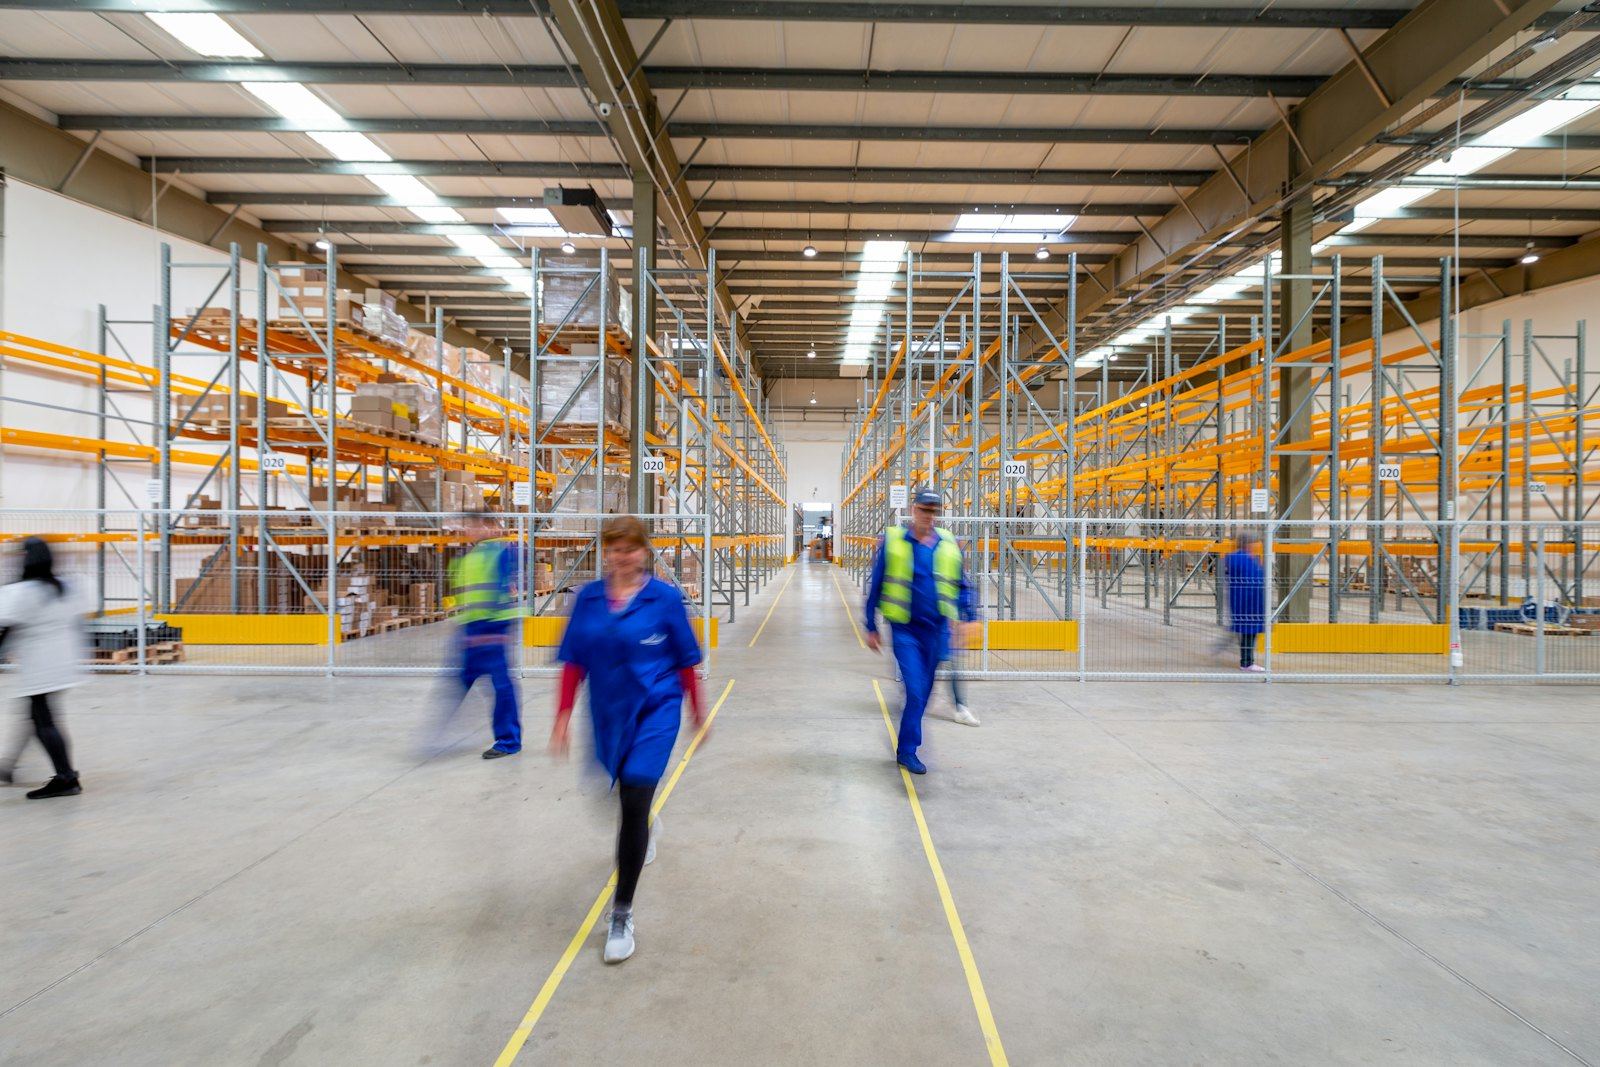
Financial due diligence is very good at one thing: confirming that the numbers in the information memorandum are real. It normalises EBITDA, picks apart one-offs and tests the working capital peg. What it rarely does is walk the warehouse floor, read the supplier contracts or ask why the planner keeps a second spreadsheet.
That gap matters more now than it did ten years ago. Bain's Global Private Equity Report 2026 makes the point bluntly. In the 2010s a typical buyout needed around 5% annual EBITDA growth to return 2.5 times its money over five years. Today, with borrowing costs of 8 to 9% and high entry multiples, Bain puts the figure at roughly 10 to 12%. Holding periods for exited buyouts now average about seven years. When the return has to come from operations and the hold is long, the operational questions stop being a nice-to-have.
Here are the ones I'd put to any target with a physical supply chain.
Where does the margin actually come from?
Financial diligence will give you gross margin by product line, perhaps by customer. It won't usually tell you the margin after the cost of serving each customer: the small-drop deliveries, the rush orders, the bespoke packaging, the returns, the sales rep who visits every fortnight. In plenty of mid-sized distributors and manufacturers, a small group of customers carries the profit and a long tail quietly erodes it. That tail is either a value-creation lever or a risk, depending on whether management knows it exists.
Ask for a cost-to-serve view, even a rough one. If nobody can produce it, that tells you something too.
How exposed is the supply base?
McKinsey's supply chain risk survey, published in December 2025, found that 95% of respondents had visibility of their tier-one supplier risks but only 42% could see as far as tier two. The same survey found 82% said new tariffs were affecting their supply chains. For a mid-market target the numbers are usually worse, because nobody owns supplier risk as a job.
Useful questions here are simple. Which five suppliers would stop the business within a month if they failed? How many of them are single-sourced? Where are their factories, and which tariff or trade regime touches them? How long would it take to qualify an alternative, and has anyone tried? EY's 2025 guidance on operational diligence asks much the same thing, and adds whether alternatives can be qualified quickly in practice as well as on paper.
What regulation is about to land on the cost base?
Financial diligence looks backwards at a historic P&L. Several UK cost lines are moving forward in ways that won't appear in last year's accounts.
Packaging extended producer responsibility is one. When PackUK confirmed the 2025/26 base fees in June 2025, plastic came in at £423 a tonne and paper or board at £196. A business that ships a lot of packaged product has a new, recurring cost that may not sit in its run-rate.
The UK carbon border adjustment mechanism is another. The government confirmed at the Autumn Budget 2025 that it starts on 1 January 2027, covering aluminium, cement, fertiliser, hydrogen, and iron and steel, with a £50,000 import threshold for registration. A fabricator importing steel needs to understand what that does to input costs before the model is signed off.
Then there is payment practice. The government's March 2026 response to its late payment consultation confirmed plans for a 60-day cap on business-to-business payment terms, applying no earlier than 2027, with exemptions including where both parties are large companies. If the target's working capital relies on stretching smaller suppliers, the peg and the cash plan both need a second look.
Can the operation scale without a step change in cost?
The equity story nearly always includes growth. The operational question is what breaks first. It might be a warehouse running at 90% of pick capacity in peak, a single production line nobody has stress-tested, a WMS on unsupported software, or a transport contract priced on volumes the business is about to exceed.
Capex is the trap. A business preparing for sale often defers maintenance and replacement spend, which flatters EBITDA and cash conversion in the final years. Walk the site. Look at the age of the racking, the forklift fleet, the compressors. Ask for the maintenance backlog, and ask the site manager rather than the CFO.
Are the savings in the plan real?
Management cases often contain a procurement saving, an inventory reduction and a footprint change. EY makes a fair point: check whether these are new, or old initiatives relaunched for the sale. Ask who owns each one, what it will cost to deliver, how long it will take, and whether the baseline is clean. Inventory reduction in particular needs testing against service levels, because cutting stock in a business with poor forecasting usually just moves the cost into expediting and lost sales.
None of this requires a three-month exercise. A focused operational workstream of a few weeks, run alongside financial and commercial diligence, can answer most of these questions well enough to price them. The worst outcome is finding them in month four of ownership, when the 100-day plan is already in front of the board.
Waterfront Advisory runs operational due diligence alongside deal teams, and the free Margin Diagnostic is a quick way to see where a target's margin pressure is likely to sit.
- Bain & Company: Private equity resurgence gathers steam as new era challenges firms to enhance value creation (Global PE Report 2026 press release)
- McKinsey & Company: Supply chain risk pulse 2025: Tariffs reshuffle global trade priorities
- EY: The questions operational due diligence should be asking in 2025
- British Retail Consortium: Packaging EPR: June announcements update
- Deloitte Taxscape: Carbon border adjustment mechanism (Autumn Budget 2025)
- Mayer Brown: UK government response to late payment consultation
More from Waterfront Advisory.
The first 100 days: where supply chain value hides in a new acquisition
Most 100-day plans are strong on governance and reporting and thin on the supply chain. That is usually where the quickest cash and the stickiest margin sit.
Read the article →
How to read your Margin Diagnostic results
Your Margin Diagnostic report gives you scores, maturity levels and pound signs. Here is what each part means, how much weight it deserves, and what to do next.
Read the article →
A practical guide to cost-to-serve
Gross margin tells you what a product earns. Cost-to-serve tells you what a customer earns once you've delivered, invoiced and chased them. The two can look very different.
Read the article →Follow us on LinkedIn.
Occasional insights from Waterfront Advisory. New articles, tools and what we are seeing across supply chains go on LinkedIn first.